CRE Idea Valuation Calculator
According to industry standards, raw ideas rarely command payment. Developers pay for risk reduction and execution capability. Use this tool to assess what you can actually sell.
Make selections and click Analyze to see your estimated market position.
You walk into a boardroom with a napkin sketch of a mixed-use complex on a vacant lot. You believe it’s the next big thing. The developers stare at you, then at their spreadsheets, and politely ask if you have any land to sell. Here is the hard truth: companies rarely pay for raw ideas. They pay for risk reduction, access, and execution capability. If you think your concept alone holds value, you are likely overestimating its market worth while underestimating the capital required to build it.
This disconnect causes countless entrepreneurs and consultants to waste years chasing "idea royalties" that never materialize. In commercial real estate (CRE), an idea is cheap; the ability to make it happen is expensive. This article breaks down exactly what CRE firms actually buy, how you can package your vision so they care, and where the money really flows in the transaction chain.
The Reality of Intellectual Property in Real Estate
Unlike software or pharmaceuticals, real estate lacks strong patent protection for concepts. You cannot patent "a rooftop bar with a vertical garden." Anyone can copy that tomorrow. Therefore, when you pitch an idea to a firm like Hines or Brookfield, they aren't buying intellectual property. They are evaluating whether your insight saves them time, money, or regulatory headaches.
Consider the difference between a generic "co-living space" concept and a specific site analysis showing that a particular block in Austin has a 15% shortage of housing for remote workers, coupled with pre-approved zoning variances. The first is a commodity. The second is an asset. Developers pay for data, not dreams. If your idea doesn't come attached to proprietary research, exclusive site control, or a unique financing structure, it has near-zero monetary value to a major player.
What Do Developers Actually Buy?
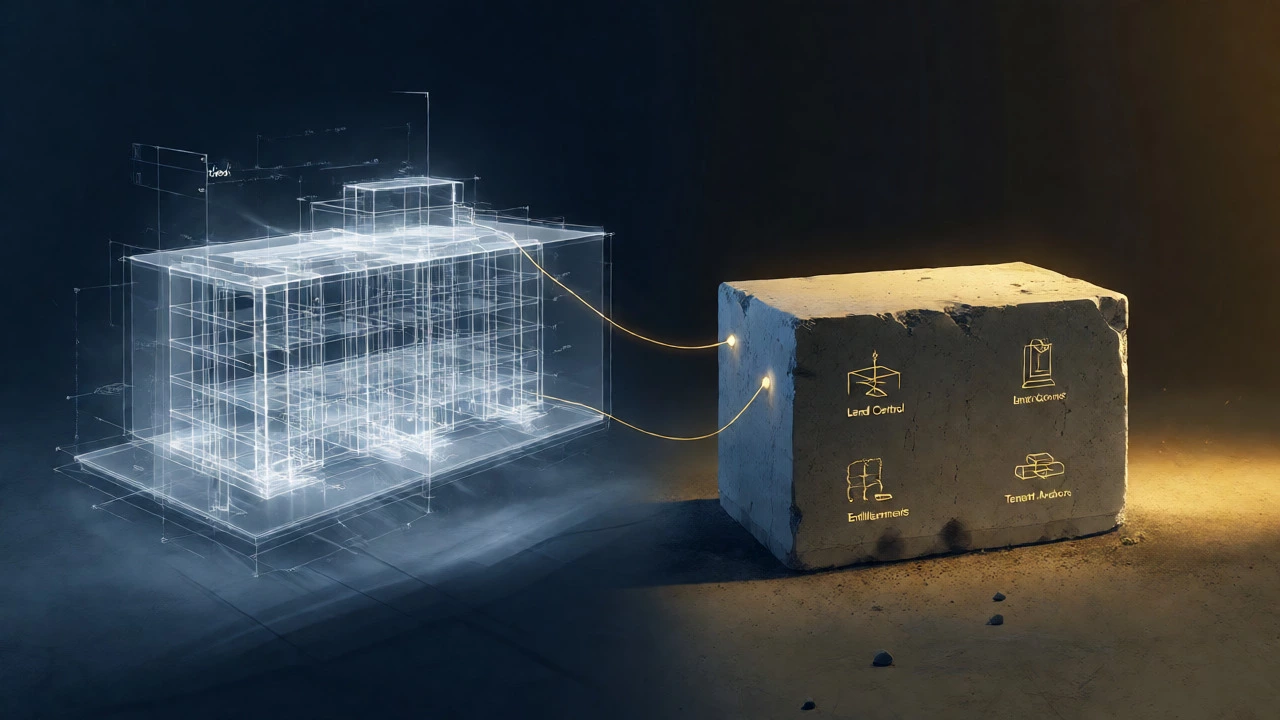
If companies don't pay for ideas, what do they pay for? Understanding this distinction is critical before you send your first email. There are three primary assets in the CRE ecosystem that command a price tag:
- Land Control: The right to develop a specific parcel. Even if the land isn't yours, securing options or letters of intent from owners gives you leverage. Developers pay premiums for sites where the title work is clean and zoning is already favorable.
- Entitlements: This is the process of getting government approval to build what you want. A raw piece of land might be worth $1 million. The same land with approved permits for a 10-story office building might be worth $3 million. That $2 million delta is the value of the "idea" executed through bureaucracy.
- Tenant Anchors: A signed letter of intent from a major tenant (like a Whole Foods or a tech startup) de-risks the project. Developers will often pay finder's fees or equity stakes to brokers who bring these tenants to the table alongside the site.
Your "idea" only becomes valuable if it helps secure one of these three things. If you can show a developer that your concept unlocks a zoning variance they didn't know existed, or brings a tenant they’ve been trying to attract for two years, you have something to sell.
Case Study: The "Idea" vs. The Execution
Let’s look at a hypothetical scenario involving a consultant named Sarah. She proposed converting old industrial warehouses in Detroit into micro-manufacturing hubs for artisans. It was a brilliant concept, fitting perfectly with the city’s revitalization goals.
Sarah approached three mid-sized developers. Two ignored her. One agreed to talk but refused to pay for the concept. Instead, she negotiated a different deal. She didn't sell the idea; she sold her role as the community liaison. Because she had relationships with local artisan guilds, she could guarantee a pipeline of tenants. The developer paid her a consulting fee to manage the tenant mix and gave her a small carried interest in the project. Her "idea" was worthless on paper, but her network made the idea executable. That is the model that works.
How to Package Your Concept for Maximum Value
If you still believe your vision has merit, you need to stop pitching it as an idea and start presenting it as a business case. Here is how to structure your proposal so a CFO takes it seriously:
- Identify the Specific Site: Don't say "urban areas need more green spaces." Say "The vacant lot at 5th and Main has poor soil quality, making traditional retail difficult, but perfect for solar-powered storage units." Specificity creates credibility.
- Run the Numbers: Include a rough pro forma. What is the estimated cost per square foot? What are the projected rents? How long until break-even? If you can’t answer these, you’re not ready to pitch.
- Show Regulatory Insight: Mention specific zoning codes or tax incentives (like Opportunity Zones) that apply. This proves you understand the landscape, not just the aesthetics.
- Define Your Role: Are you asking for a lump sum? Equity? A success fee? Be clear about what you want in exchange for your input.
Remember, developers are risk-averse. They lose millions on failed projects. Your job is to lower their perceived risk. The more concrete evidence you provide, the less they feel they are gambling on a hunch.
Alternative Paths to Monetizing Vision
If selling the idea outright feels impossible, consider other structures. Many successful ventures start with a partnership rather than a sale. You might form a joint venture (JV) where you contribute the "soft costs" (research, design, initial approvals) and the developer contributes the "hard costs" (construction capital).
Another option is licensing your brand. Think of boutique hotel groups like Ace Hotel or citizenM. Their value isn't just the buildings; it’s the curated experience and operational playbook. If your idea includes a unique operational model, you might license that system to a landlord who owns the bricks but lacks the hospitality expertise.
| Component | Developer Perception | Monetization Potential |
|---|---|---|
| Raw Concept/Design | Commodity; easily replicated | Low to None |
| Market Research Data | Useful but internal teams can replicate | Low (Consulting Fee) |
| Zoning/Entitlement Strategy | High value; reduces timeline risk | Medium (Success Fee/Equity) |
| Secured Tenant Anchor | Critical; ensures cash flow | High (Brokerage Commission/Equity) |
| Controlled Land Option | Essential; controls the asset | Very High (Flip Profit/JV Stake) |
Pitfalls to Avoid When Pitching
One common mistake is demanding exclusivity too early. If you tell a developer, "You must sign an NDA before I tell you my idea," you’ll get shut out. Most NDAs in CRE are weak because information leaks anyway. Better to share enough detail to prove competence without giving away the entire execution plan.
Another trap is ignoring the capital stack. Your idea might be great, but if it requires $50 million in equity and you’re pitching to a firm that specializes in $5 million deals, you’re wasting everyone’s time. Match your vision to the investor’s capacity. A neighborhood shopping center needs a different buyer profile than a downtown skyscraper.
Final Verdict: Who Gets Paid?
So, will companies pay for ideas? Only if those ideas are wrapped in execution. The person who gets paid is usually the one who solves the hardest part of the puzzle: finding the land, securing the permits, or locking in the tenants. If you can do that, you’re not just an idea guy-you’re a developer. And developers get paid well.
If you’re sitting on a vision, stop looking for a buyer for the thought itself. Start looking for partners who need what you have: either the knowledge to navigate red tape or the connections to fill the building. That is where the real money lives.
Do real estate developers sign Non-Disclosure Agreements (NDAs)?
Rarely for initial pitches. Most developers receive dozens of proposals weekly and find NDAs cumbersome. They prefer open conversations where they can quickly assess fit. If they are interested, they may sign a formal agreement later during due diligence, but expecting an NDA upfront often signals naivety.
Can I sell a architectural design concept separately from the land?
Yes, but typically only if the design is highly distinctive or patented. Usually, architects are hired by developers after the land is secured. Selling a standalone design requires proving that the aesthetic or functional layout adds measurable value (e.g., higher rent premiums) that outweighs the cost of hiring a new architect.
What is a 'carried interest' in real estate?
Carried interest is a share of the profits given to the general partner (the manager) or key contributors after investors receive their initial capital back plus a preferred return. For someone contributing an idea or management expertise without cash, negotiating a small carried interest (e.g., 5-10%) is a common way to align incentives and earn rewards if the project succeeds.
How much should I charge for a feasibility study?
Fees vary widely based on complexity and region, ranging from $5,000 for a basic high-level review to $50,000+ for detailed financial modeling and market analysis. However, many developers prefer to pay via success fees or equity stakes rather than upfront cash for studies from unproven entities, to mitigate their own risk.
Is it better to pitch to large firms or private investors?
Private investors and smaller boutiques are often more agile and willing to take risks on novel ideas. Large institutional firms (like Blackstone) have rigid investment committees and strict criteria, making them harder to impress with unconventional concepts unless the scale is massive. Start with smaller players who can move faster.